Reading dog body language in group play: a guide for daycare staff
Learn to spot healthy play, early stress signals and the ladder of aggression, and how to step in calmly before play goes wrong.
By the PackDay team. Checked against the sources listed at the end.
Card fees, booking fees and platform fees all come out of the same takings. Here’s how to tell them apart, what changed with card surcharges in October 2026, and how to work out what you really pay.
When a client pays for daycare by card, two different kinds of fee can be taken from that payment. It helps to keep them apart in your head, because they behave very differently over time.
Card processing fees, sometimes called merchant service fees, are what your payment provider charges to move the money. They bundle together the interchange fee paid to the bank that issued the card, the scheme fee paid to the card network, and the provider’s own margin. Every business that takes cards pays these in some form.
Booking or platform fees are charged by your software company. They are usually a percentage of each booking, or of each payment taken through the system. Some providers fold them into a single “payments” rate, so they look like card fees. They aren’t. They are a charge for using the software, and they grow every time your business grows.
A flat monthly subscription costs the same whether you have a quiet July or a packed December. A percentage fee quietly rises with every new client, every price increase and every extra day a dog attends.
Until recently, Australian businesses could add a surcharge to card payments, as long as it didn’t exceed what it cost them to accept that type of card. The ACCC enforced that rule.
The Reserve Bank of Australia finished its review of merchant card payment costs and surcharging in March 2026. The changes that took effect on 1 October 2026 are:
More changes are already scheduled. Card networks and large payment providers must start publishing their fees, with the first reports due by 30 October 2026. Standardised fee information on merchant statements, and caps on interchange for foreign cards, start on 1 April 2027.
You still have options. The ACCC says you can offer a discount for a cheaper way to pay, such as cash or PayID, as long as the full price is shown prominently and the discount is clearly disclosed. You can also raise your prices to cover card costs, as long as you don’t mislead people about why. The new rules apply only to card payment surcharges, not to other fees.
What this means in practice: every fee on a card payment now comes straight out of your margin, unless you build it into your prices. The RBA expects lower interchange caps to help businesses, especially small ones, which are usually charged the highest costs. Whether you see that saving depends on your plan and your provider. The RBA suggests checking you are on the best plan and shopping around.
Here is an example. Say your software takes a booking fee of 1.3% of every payment it processes. This is on top of your card processing fees, not instead of them.
| Monthly card takings | Booking fee per month | Booking fee per year |
|---|---|---|
| $10,000 | $130 | $1,560 |
| $30,000 | $390 | $4,680 |
| $60,000 | $780 | $9,360 |
The numbers are illustrative, but the pattern is real. Double your takings and you double the fee, even though the software is doing the same job it did last year. At $60,000 a month, that example fee alone would cover a lot of casual shifts.
Try this: find last month’s card takings, multiply by your software’s percentage fee, then multiply by 12. That’s what the software costs you each year before you add its subscription.
Before you sign, or before your next renewal, ask these questions and get the answers in writing.
If a provider can’t give you a straight answer to any of these, treat that as an answer.
Your effective rate is the total you pay in fees, as a percentage of the money you take by card. It’s the only number that lets you compare providers fairly, because it includes everything, not just the headline rate.
Here is a worked example with made-up numbers. Card takings for the month are $30,000. The payment provider charged $310 in transaction fees and $40 in terminal rental. The booking software took $390. Total fees are $740. $740 divided by $30,000, multiplied by 100, gives an effective rate of about 2.47%.
If your effective rate is well above your headline rate, look for the extras: monthly minimums, separate fees for certain cards, or a software percentage you had forgotten about. From April 2027, standardised merchant statements should make this easier to see.
How PackDay will do it: one flat monthly price. No booking fees, no transaction fees and no per-user fees, ever. Texts over your plan’s allowance will be held, never billed by surprise.
Try the calculator on our home page with your own numbers.
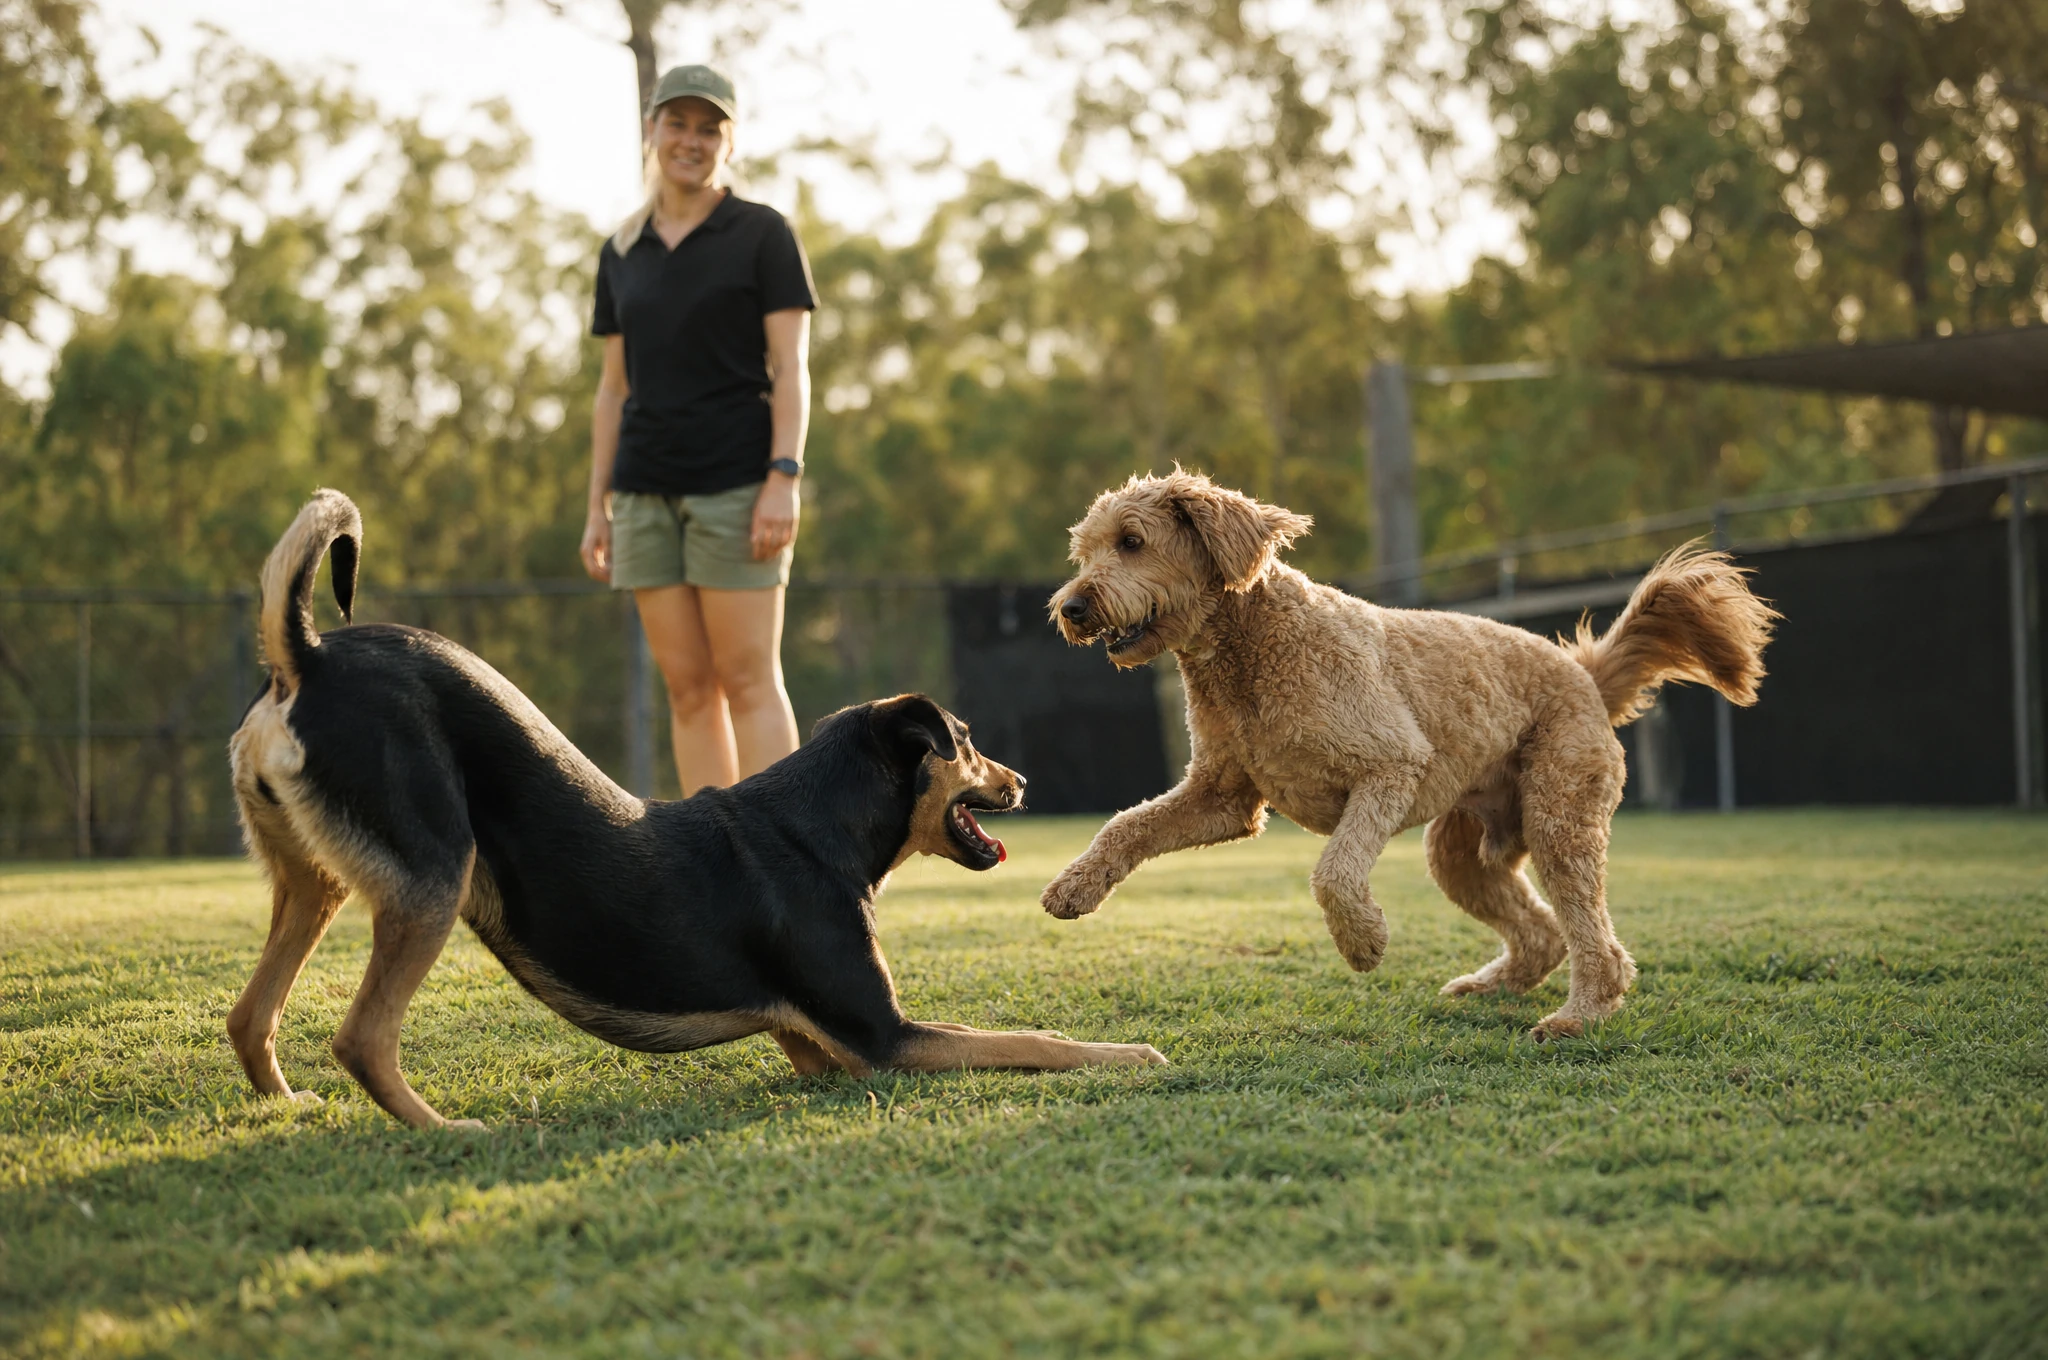
Learn to spot healthy play, early stress signals and the ladder of aggression, and how to step in calmly before play goes wrong.
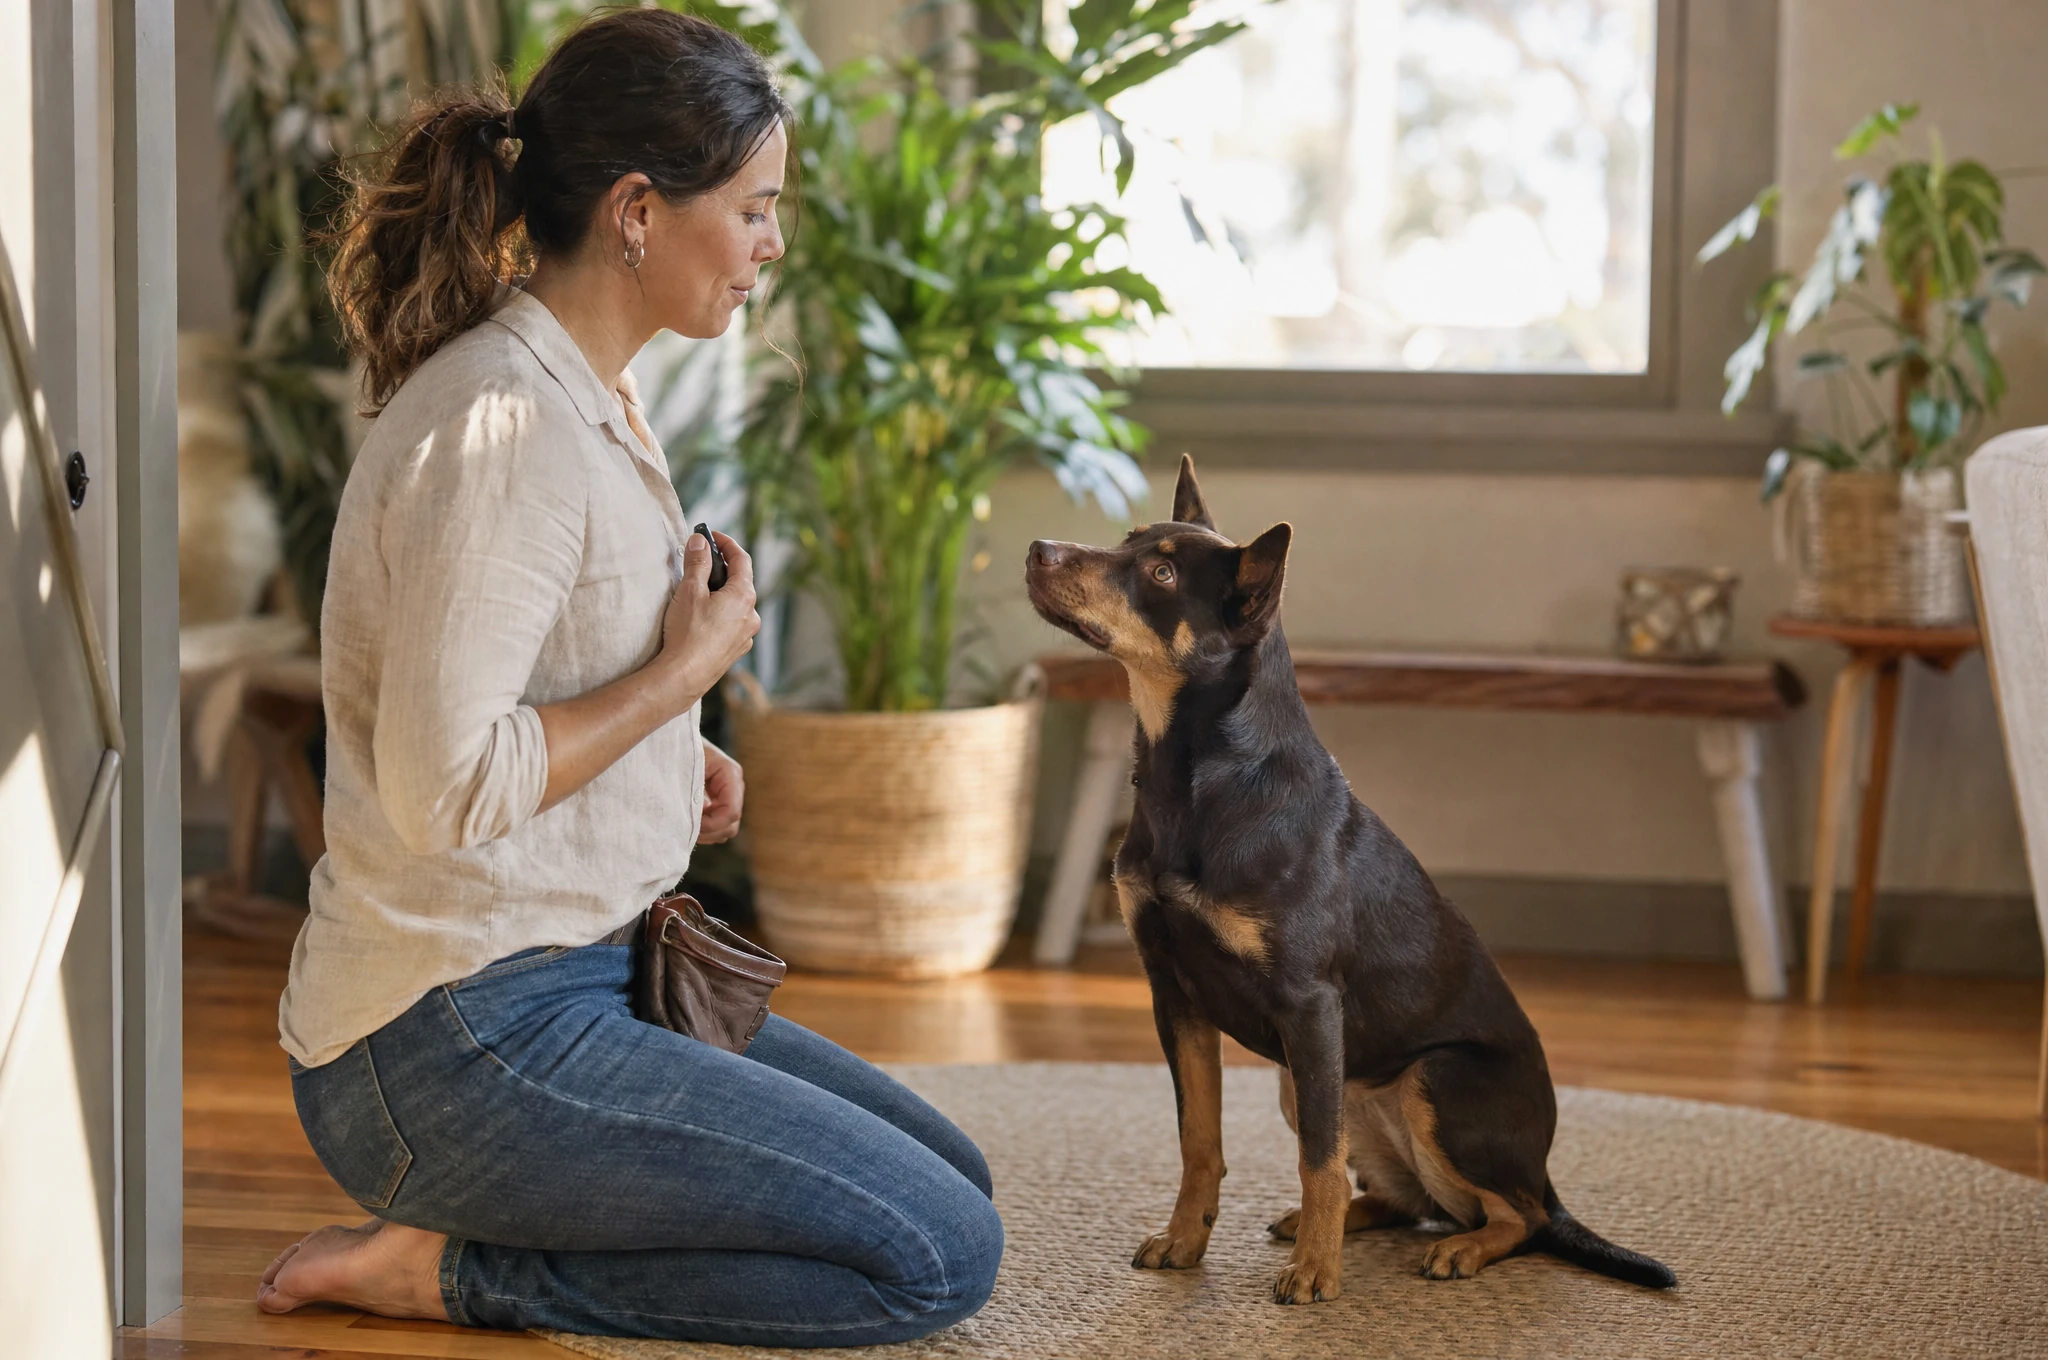
What a marker is, how to charge a clicker, and three first behaviours you can teach in short, five-minute sessions.
A 30-day free trial when PackDay opens, no card. No booking fees, ever.